Limited Company Buy-to-Let Mortgage: UK Landlord Guide
Purchasing rental property through a limited company has become increasingly popular among UK landlords over the past decade. A limited company buy-to-let mortgage allows landlords to finance property purchases through a corporate structure rather than personal ownership, fundamentally changing how rental income is taxed and how borrowing works. Whether you're expanding an HMO portfolio or acquiring your first multi-occupancy property, understanding how these mortgages operate is essential for making informed investment decisions in 2026.
Why Landlords Choose Limited Company Structures
The shift towards limited company buy-to-let mortgages accelerated significantly after changes to mortgage interest relief for individual landlords. Prior to these changes, landlords could deduct all mortgage interest from rental income before calculating tax. The new rules restrict relief to a tax credit, making higher-rate taxpayers particularly affected.
Corporate ownership offers several distinct advantages:
- Rental profits are subject to corporation tax rather than income tax
- Full mortgage interest remains deductible as a business expense
- Retained profits can be reinvested without personal tax liability
- Succession planning and portfolio transfer become more straightforward
- Multiple directors can share ownership cleanly
However, limited company ownership isn't universally beneficial. You'll face incorporation costs, annual accounts requirements, and potentially higher mortgage rates. The decision depends heavily on your personal tax position, portfolio size, and long-term investment strategy.
Tax Considerations for Company-Owned Property
When operating through a limited company, rental income becomes corporate revenue. You'll pay corporation tax on profits after deducting allowable expenses including mortgage interest, maintenance costs, and professional fees. The HMRC Property Income Manual provides comprehensive guidance on how rental income taxation operates across different ownership structures.
Extracting profits from your company creates additional tax events. Drawing a salary triggers income tax and National Insurance, whilst dividends incur dividend tax. Many landlords balance these methods, taking a modest salary and supplementing with dividends to optimise overall tax efficiency.
Capital gains also operate differently. When the company sells a property, any gain forms part of taxable profits subject to corporation tax. Unlike personal ownership, there's no annual capital gains tax allowance available to companies.
Understanding Limited Company Buy-to-Let Mortgage Criteria
Lenders approach limited company buy-to-let mortgages differently from personal mortgages. The company itself becomes the borrower, and underwriting focuses on both corporate and personal factors.
| Assessment Factor | Personal Mortgage | Company Mortgage |
|---|---|---|
| Borrower | Individual | Limited company (SPV) |
| Income assessment | Personal earnings | Rental income projections |
| Affordability test | Personal commitments | Interest coverage ratio |
| Credit check | Personal credit only | Directors' credit + company |
| Guarantees | Usually none | Often personal guarantee required |
Most lenders require the company to be a Special Purpose Vehicle (SPV) – created specifically to hold property investments. They typically won't lend to trading companies or those with complex business activities. The Provestor guide to limited company buy-to-let mortgages explains how SPV structures must align with lender expectations, including appropriate SIC codes and shareholding arrangements.
Interest Coverage and Affordability
Rather than assessing your personal income, lenders calculate interest coverage ratios. They'll typically require projected rental income to exceed mortgage interest by a specific percentage, commonly between 125% and 145% of the interest payment.
For HMO properties, this calculation can be more complex. Lenders recognise that room-by-room letting generates higher yields but may also require larger coverage ratios to account for perceived higher risk and potential void periods.
Directors' personal credit history remains relevant even though the company borrows. Most lenders require all directors and shareholders to provide personal financial information and often demand personal guarantees, meaning you remain liable if the company defaults.
Setting Up Your Limited Company Structure
Before approaching mortgage lenders, you'll need to establish your company correctly. Most landlords form a private limited company through Companies House, selecting appropriate Standard Industrial Classification codes that clearly indicate property investment activity.
Essential incorporation steps include:
- Choosing a company name (check availability at Companies House)
- Appointing at least one director and shareholder
- Registering for corporation tax with HMRC
- Opening a dedicated business bank account
- Establishing proper accounting systems and records
The company requires a registered office address in England or Wales. This becomes a matter of public record, so many landlords use their accountant's address or a professional registered office service rather than their home.
Shareholding structure matters for both tax planning and mortgage approval. Some lenders prefer simple structures with one or two individual shareholders rather than complex corporate shareholdings or multiple parties.
Ongoing Compliance Requirements
Operating a limited company brings regulatory obligations beyond those facing individual landlords. You'll need to file annual accounts with Companies House and submit corporation tax returns to HMRC. Maintaining proper separation between personal and company finances is crucial.
Many landlords managing HMO portfolios find that software specifically designed for property management helps track rental income, expenses, and compliance documentation. The Landlord Founding Package provides comprehensive tools for managing multiple properties through a company structure, with features that help generate reports suitable for both company accounts and mortgage refinancing applications.
Your company must also comply with all standard landlord obligations. Properties require proper licensing where applicable, safety certificates remain mandatory, and tenant management follows the same legal framework regardless of ownership structure. The RICS guidance on lettings provides authoritative professional standards that apply to all landlords operating rental businesses.
Finding and Applying for Company Mortgages
The limited company buy-to-let mortgage market differs from mainstream residential lending. Fewer lenders participate, and products often come from specialist divisions or smaller building societies rather than high-street banks.
Interest rates typically run higher than personal buy-to-let mortgages, reflecting perceived additional risk and the specialist nature of lending. However, rates remain competitive, and the tax advantages often outweigh the slightly higher borrowing costs for higher-rate taxpayers.
Working with Mortgage Brokers
Given the specialist nature of company lending, most landlords work with mortgage brokers who have specific experience in this sector. These brokers maintain relationships with lenders active in the company buy-to-let market and understand each lender's specific criteria around SPV structures, HMO properties, and portfolio landlords.
Brokers can navigate complex situations such as multi-unit HMOs, properties requiring licensing, or portfolios split between personal and company ownership. They'll also advise on timing your application relative to company formation and accounts preparation.
Preparation significantly affects approval chances. Lenders want to see established companies with filed accounts, though some will lend to newly formed SPVs if directors have strong personal finances and property investment experience.
Additional Costs and Stamp Duty
Beyond standard mortgage fees, limited company buy-to-let mortgages involve additional costs worth factoring into your investment calculations.
Typical cost categories include:
- Higher mortgage arrangement fees (often 1-2% of loan value)
- Legal fees for both purchase and mortgage (companies require commercial conveyancing)
- Accountancy fees for annual accounts and tax returns
- Companies House filing fees
- Professional registered office services (if used)
Stamp Duty Land Tax presents a significant cost difference. Companies purchasing residential property face an additional surcharge on top of standard rates. The GOV.UK guidance on SDLT for corporate bodies explains how these higher rates apply and when certain exceptions might be available.
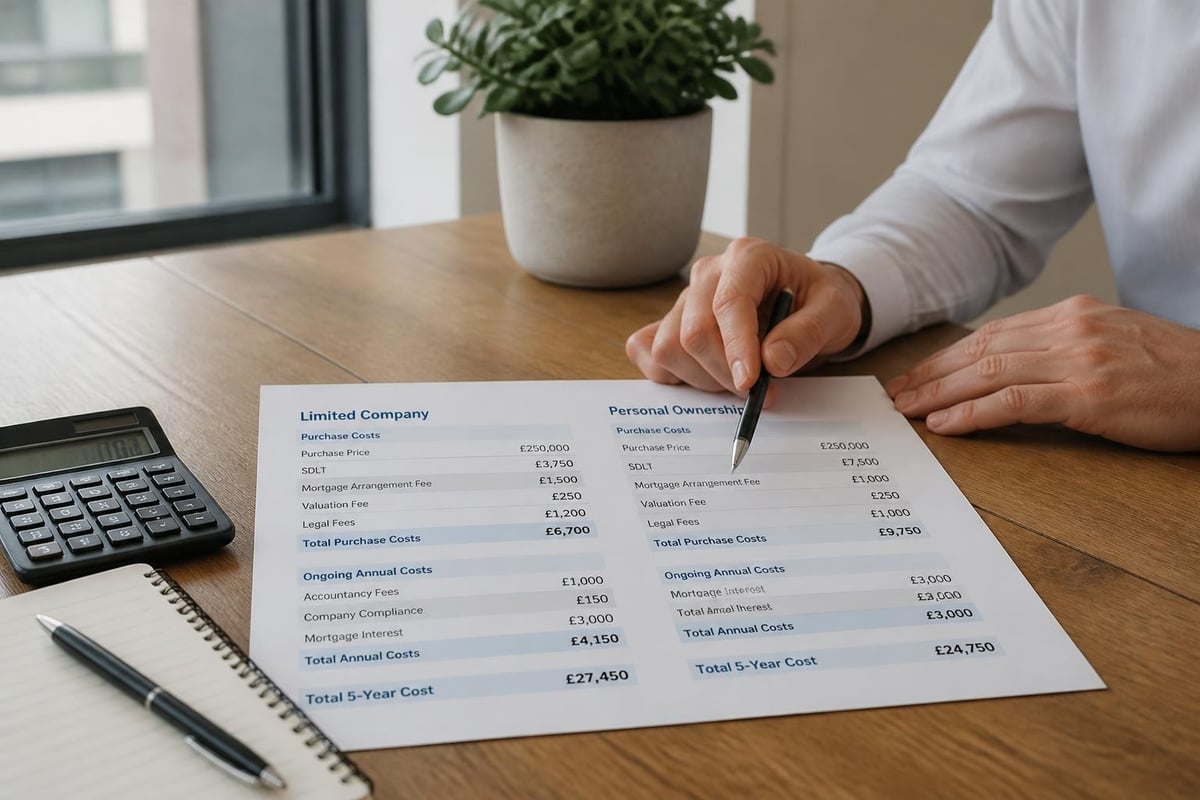
For HMO landlords, these upfront costs can be substantial but should be weighed against long-term tax savings and the operational flexibility company ownership provides. Detailed financial modelling helps determine the break-even point where company ownership becomes financially advantageous.
Portfolio Growth Through Company Ownership
Many landlords find that limited company structures facilitate portfolio expansion more effectively than personal ownership. Retained profits can be reinvested in additional properties without triggering personal tax charges, and lenders often view growing property companies more favourably than individuals with multiple mortgages.
When scaling an HMO portfolio, company ownership provides clearer financial reporting. Professional accounts preparation creates transparent records of rental income, occupancy rates, and profitability across multiple properties. This documentation proves valuable when approaching lenders for additional finance or when seeking to refinance existing company-owned properties.
Mixing Personal and Company Property Ownership
Some landlords operate hybrid portfolios with certain properties held personally and others through limited companies. This approach offers flexibility but creates complexity in management and tax reporting.
Transferring personally-owned property into a company triggers Capital Gains Tax and Stamp Duty Land Tax, making wholesale portfolio transfers expensive. Most landlords maintain existing personal holdings whilst channelling new acquisitions through company structures.
Managing mixed portfolios requires careful record-keeping to ensure rental income, expenses, and maintenance costs are correctly allocated to the appropriate tax return. Robust systems that track properties by ownership entity become essential as portfolios grow.
Refinancing and Portfolio Management
Limited company buy-to-let mortgages typically follow similar terms to personal mortgages, with two or five-year fixed rates being common. When fixed periods end, you'll need to remortgage or move to the lender's standard variable rate.
Refinancing company-owned property requires up-to-date company accounts and often a fresh valuation. Lenders reassess interest coverage ratios based on current rental income, making strong rent roll documentation important for securing favourable refinancing terms.
Key refinancing considerations include:
- Company accounts must be filed and current
- Rental income should meet interest coverage requirements
- Property values affect loan-to-value ratios and available rates
- Director circumstances and credit history remain relevant
- Some lenders offer preferential rates for existing company borrowers
Market conditions in 2026 mean landlords should review their mortgage arrangements regularly. Even modest rate reductions can significantly impact profitability across multi-property portfolios, particularly for HMOs with higher mortgage borrowing relative to property values.
Exit Strategies and Long-Term Planning
Unlike personal ownership where properties typically pass through inheritance, company-owned portfolios offer alternative succession options. Shares can be transferred or gifted gradually, potentially reducing inheritance tax exposure whilst maintaining continuity of the rental business.
Winding up a property company involves disposing of assets and distributing proceeds to shareholders. This process triggers corporation tax on any capital gains, followed by potential tax charges on distributions. Professional tax advice becomes crucial when planning company dissolution to minimise overall tax liability.
Some landlords ultimately prefer to retain company structures indefinitely, using them as long-term vehicles for property wealth that can pass to future generations or be sold as operating businesses rather than merely property assets.
Limited company buy-to-let mortgages offer UK landlords significant tax and operational advantages, particularly for those managing HMO portfolios and multiple properties. Whilst higher borrowing costs and additional administrative requirements exist, the long-term benefits often justify the additional complexity for landlords with substantial rental income. Whether you're structuring your first company purchase or expanding an established portfolio, Astenda provides the management tools you need to track finances, maintain compliance, and efficiently operate your property business through any ownership structure.
Get a live view of your whole property portfolio.
Start your 30-day free trialGeneral information only. This is not legal, tax or financial advice. Rules change and vary by council, so check GOV.UK or take professional advice.